
Are electricity markets fit for the purpose of being a catalyst in accelerating the clean energy transition of our electricity system? The stakes couldn’t be higher — urgent and large-scale electrification of all energy use supported by a deep decarbonisation of the electricity sector is essential for climate change mitigation.
This five-part series dives deep into the economics of electricity markets and the role that markets can and must play in the decarbonisation journey. But in reality, do they? And what can be done about it?
This first part, Designed for the past sets the stage by recounting the history of electricity markets and highlights the inadequacy of current market framework in playing that crucial role in our decarbonisation journey.
In July 2024, I stumbled upon an opinion piece by FT’s chief economics commentator and eminent financial journalist Martin Wolf, headlined Market forces are not enough to halt climate change. Drawing insights from the latest policy briefs and data showing the recent global slowdown in renewable energy projects, Martin argues that, left to itself, “the energy market alone” will not fix the global failure to incentivise pro-climate growth.
I was intrigued by the argument. Not because I disagreed with it (and not due to a lack of trying!), but because it ended on a somewhat hopeless note. Martin concludes that today’s geo-political fragmentation at the global stage and domestic populism within countries implies that we (read, humanity) lack the courage and conviction necessary to fix the tragic market failure behind the slowdown in clean energy transition.
After having spent a large part of my PhD studies thinking about and proposing new market designs and pricing mechanisms in the electricity markets, specifically to accommodate the challenges that renewables bring, I couldn’t stop myself from reflecting on his remarks.
There has to be a market-based fix to this global challenge, I wondered. A free market is, after all, the best coordination mechanism we have discovered so far to steer rational and self-interested actors towards building social utility. That competitive markets, guided by the proverbial invisible hand, are highly effective at organising economic activities such that truthful disclosure of preferences and costs, is not just evidence-backed but even mathematically provable.
When it comes to electricity, the competitive wholesale markets that we know today (mature markets in Europe and North America, for example, and emerging ones such as in India and South America) have followed a series of liberalisation and deregulation reforms of the sector, starting in the early 1990s.
If you’re interested to dive deeper, this article provides succinct account of the historical development of electricity markets, anchored in a comparison between the European and North American market design philosophies and how they can be expected to fare in the future context of low-carbon electricity systems.
Our ongoing efforts to achieve the transition of energy systems towards renewable energy sources rely heavily on these market-based activities. However, it is now painfully clear that this transition is not occurring at the scale and pace necessary to reach our climate change mitigation targets.
If you’re interested in a reality check on climate change, and specifically it’s compatibility with the recent massive growth in AI, you are welcome to read my recently-published write-up:
Climate Change and an AI-hooked Society: A Compatibility Check
Globally, commercial activities around investments in renewable energy projects are not showing encouraging signs.
For instance, in Denmark, the undisputed global pioneer of wind energy, no bids at all were received for an auction of rights to develop 3 GW of offshore wind in adjoining North Sea. This was the first in a series of two auctions of 3 GW each, with a potential for developers to overplant (i.e., exceed the installation goal) up to 10 GW.
This auction series was deemed historic by the auction organiser, Danish Energy Agency, for two reasons. First, due to the fact that the total planned installed capacity exceeded the current average electricity demand of the entire country by a long shot. Second, it was intended to open up avenues for electrification of hard-to-abate sectors via Power-to-X, thus significantly boosting the green hydrogen economy in Europe.
While the fate met by this auction call was not surprising to many of us who are active in the Danish energy landscape, it undoubtedly (and thankfully!) drew attention to a few fundamental questions on the viability of our current approaches to stimulate investment in clean energy which must be addressed urgently. (More details on that in an upcoming post!)
Beyond Denmark, recent geopolitical developments have brewed a perfect maelstrom, caused by the pressure in global supply chains and growing uncertainty perceived by the global financial systems, which hinders renewable energy projects from seeing the light of the day.
In fact, in April 2025, the US Department of Interior issued an immediate stop order to Equinor to halt work on an already-approved, under-construction 810 MW offshore wind project — a project in which Equinor has already spent $2bn and was expecting to start producing power as early as 2027!
Thankfully, the stop work order was lifted later in May 2025 after extensive dialogue and construction work has resumed. But not without sending damaging ripples of uncertainty and anxiety across the energy supply chain!
Such a cold (and short-sighted) response to a rapidly warming planet brings me to this article series, which above all, is an attempt to reconcile the dilemma brewing in my head over the last several months.
It is clear to me that while we have conquered the technological barriers to clean, zero-carbon energy for all, we are losing the battle against economics and geo-politics of the energy transition.
And this is a battle we cannot afford to lose — because electricity generation is by far the easiest and most mature decarbonisation tool we have at our disposal to reduce our carbon emissions as a society.
Therefore, deeper electrification of all energy usage coupled with rapid decarbonisation of the electricity system is crucial to ensure the continued prosperity of our future generations!
While I strongly believe that efficient market-based activities are critical to delivery of clean energy to consumers, the more I reflect on the current state of energy markets and on the long-run investment signals generated by them, I conclude that our energy markets are clearly not fit for purpose. The purpose of being a catalyst in enabling the rapid and urgent large-scale transition to cleaner sources of electricity.
And this is not surprising.
Designed for a former era of fossil fuels when fuel costs governed energy prices, cracks in the foundational structures of the market design start showing up in the new paradigm dominated by zero fuel cost (and zero opportunity cost) weather-dependent, renewable energy, such as wind and solar photovoltaics (PV).
So, what can and must be done about them?
One of the works Martin cites in his article is Brett Christophers’ recently-published book, The Price is Wrong: Why Capitalism Won’t Save the Planet.
The book meticulously crafts a rather provocative narrative of how the market-based approach has not and will not lead to reaching climate change mitigation targets, given the technological, regulatory, and financial milieu the electricity system operates in.
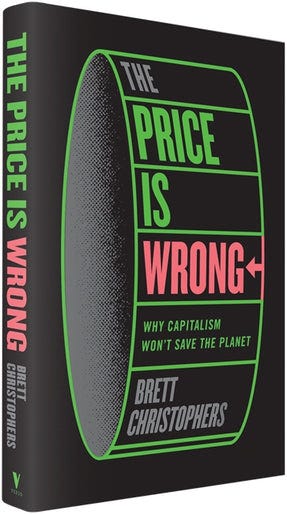
Brett’s thesis is a demonstration, via a rather sophisticated yet solid chain of arguments that — without financial support from governments, renewables have not and will not get built at scale.
In fact, he goes as far as saying that only the state has the financial and logistical capabilities to deliver the trillions of dollars of investment annually needed in wind and solar projects to prevent a catastrophic climate outcome for the planet.
Notwithstanding the clear leftist inclination of the work, I wholeheartedly recommend the book to anyone seeking to understand the nitty-gritty of the geopolitics stifling the global clean energy transition.
Personally, the book left a lasting impression on me. In particular, due to the breadth of sources Brett relies upon to drive across the point that current electricity markets are hindering the clean energy transition.
What emerges from the narrative is that the failure of markets is so stark and shocking that the very mechanisms we have devised to competitively and efficiently enable the transaction of large volumes of energy are becoming the irrelevant middle person in the transaction between producers and consumers.
And this is clearly evident from the increasing share of long-term, fixed-price backed Power Purchase Agreements (PPAs) becoming the cornerstone of successful renewable energy projects.
Without the revenue stability guarantee provided by such PPAs, investors and banks, having well-meaning intentions to provide the needed financial backing for these large-scale capital-intensive projects, develop cold feet.
To understand why this happens, one needs to dive into the economics of such renewable energy projects.
After all, it is the outcome of economic assessments made by investors and banks that ultimately decides whether a project gets built successfully and starts producing clean energy.
First, let’s take a look at the expenses side of this economic picture in the next part in this series “Part II: The incompleteness of LCOE”.
Are electricity markets fit for purpose? Part II: The Incompleteness of LCoE
<hr><p>Are electricity markets fit for purpose? Part I: Designed for the past was originally published in Clean Energy for Billions on Medium, where people are continuing the conversation by highlighting and responding to this story.</p>